
- Rating
- 4.6
- 4.7K Reviews
- Downloads
- 1M+
- Age Rating
- Everyone
App Specs
- Version
- 26.32.0
- Updated
- Requires
- 11
- Price
- Free
Screenshots
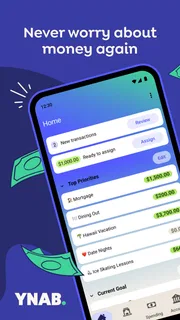
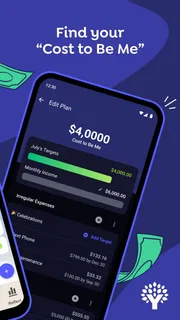
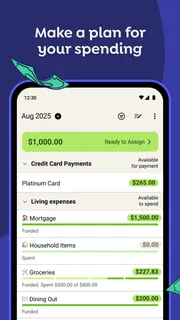
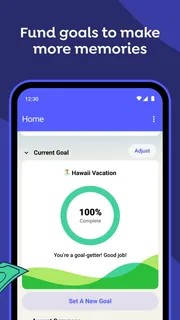
Our Review
 Analysis byMileapps
When I judge a budgeting app, I look beyond the totals: can I find what I need, make a decision without wrestling with the screen, and keep going when life gets busy? That’s the lens I bring to YNAB, a finance app from ynab.com built around assigning money to specific jobs. Its method can make budgeting feel more active than simply checking a balance, which is useful for people who want a plan they can revisit and adjust.
The app has a 4.5 average from around 24,000 ratings, and it has been installed over a million times. It is free to download, rated for Everyone, and offers in-app purchases from $14.99 to $109.00 per item. I’d treat the free download as a chance to explore the approach, then look carefully at the purchase terms before deciding whether it fits my finances. The current version is 26.5.1, and it requires iOS 11 or later.
Finding your way through a hands-on budget
I find the most useful way to approach this budget is to treat it as a series of small choices, not a monthly cleanup project. When I review a category, I can ask whether its amount still reflects what matters this week, then adjust priorities while the trade-off is clear. That habit is especially helpful when plans shift, and it leads naturally into how repeated screen interactions feel in everyday use.
Readability and navigation: a plan, not just a balance
Right off the bat, setting up YNAB is pretty straightforward. You start by linking your bank accounts, which, I know, might sound a bit daunting, but the process is smooth and secure. The app does a great job of guiding you through each step, so even if you’re not the most tech-savvy person out there, you’ll find it pretty manageable.
Once your accounts are linked, it’s all about creating your budget. YNAB uses a unique approach called "zero-based budgeting," which essentially means giving every dollar a job. At first, it might feel a bit restrictive, but trust me, it’s liberating once you get the hang of it. You start to see where your money goes and, more importantly, where it should go.
That setup changes what I expect from the main budget view. Rather than treating the account balance as permission to spend, I have to look at the amount assigned to the category I’m about to use. If groceries have a set amount and a household bill is coming up, the distinction matters: money sitting in a bank account may already have a purpose. For someone who tends to spend from the headline balance and regret it later, that extra check can be a useful pause.
I’d also approach the first budget as a working draft, not a test I have to pass. Start with categories that reflect actual decisions—housing, food, transport, recurring bills and near-term plans—then make room for expenses that arrive irregularly. If an estimate is wrong, adjusting it is part of budgeting, not evidence that the plan failed. That framing makes the learning curve feel less like a demand for perfect bookkeeping.
Motor and sensory considerations: fewer surprises through routine
Budgeting involves repeated small actions: checking a category, recording or reviewing a purchase, and deciding whether to move money between priorities. That can be tiring if precise tapping or frequent screen changes are difficult. I’d recommend trying a short routine at a comfortable pace rather than attempting to process a whole month of transactions at once. A brief review after a shopping trip can be easier to manage than a long catch-up session.
The manual attention involved has a trade-off. It gives me a reason to notice what a transaction means instead of accepting an automated label without review, but it also asks more of my hands and concentration. Anyone who finds repetitive entry uncomfortable should consider whether this style of budgeting feels sustainable. The method is most helpful when the upkeep is small enough to repeat; a theoretically detailed budget that becomes exhausting is not much of a plan.
For readers who use larger text, a screen reader, voice control or other device-level accessibility settings, I would test the actual screens and key tasks before relying on the app for daily money decisions. A budget is personal and time-sensitive, so it matters whether category names, amounts and controls are clear in the way you use your phone. I wouldn’t assume that a guided setup alone answers those questions; the practical test is whether you can comfortably review and change a category yourself.
Situational access: budgeting around real life
One everyday scenario shows where the method earns its keep. Imagine payday arrives while a grocery run, a utility bill and a planned repair are all approaching. Instead of treating the new balance as spare cash, I can assign money to the obligations first, then see what remains for groceries or flexible spending. If the repair costs more than expected, the budget makes the choice explicit: I need to move money from another category rather than quietly pretending the original plan still works.
That makes the app a better fit for people who want to make trade-offs visible, especially when income is variable or several priorities compete for the same dollars. It can also help a household have a more concrete conversation: “Which category should change?” is easier to act on than a vague warning to spend less. On the other hand, a person who only wants a quick account balance or an effortless snapshot may find the extra planning unnecessary.
Compared with a basic spreadsheet, YNAB gives the budgeting process a more guided structure, but a spreadsheet may suit someone who wants complete control over layout and formulas. Compared with a simple expense tracker, the emphasis here is on deciding what available money is for, rather than mainly looking back at where it went. That forward-looking focus is the point, but it also means the app asks for more engagement than a passive tracker. If automatic categorization is the main feature you want, another style of finance app may feel more convenient.
Remaining barriers: effort, cost and questions worth asking
My strongest practical caution is the ongoing attention the method requires. Manual review can improve awareness, but it can also create a backlog if I ignore transactions for weeks. A useful habit is to check in after spending and again when planning the next pay period, then handle unusual purchases while I still remember what they were. This is not about entering every detail obsessively; it is about keeping the plan close enough to reality that category balances remain useful.
Before committing, I’d ask myself three things: Do I want to assign money before spending it? Am I willing to review and adjust categories as plans change? And does the purchase price make sense for the value I expect from a budgeting routine? If the answer to the first two is no, a simpler tracker or a spreadsheet may be a better match. If they are yes, I’d still begin with a small number of meaningful categories and test whether the workflow fits my week.
People also wonder whether they need to link accounts. The setup described in the app begins with linking them, but the more important decision is whether that feels comfortable and useful for the way they manage money. If connecting accounts makes you uneasy, pause and review the available setup choices in the app before building a process around it. Either way, the budget only helps if the figures and categories are kept current enough to guide decisions.
An inclusive verdict: useful when the workflow fits
One of the standout features of YNAB is its focus on teaching financial discipline. The app doesn’t just help you budget; it actually educates you on money management. There are plenty of tutorials and workshops available, which are super helpful if you’re trying to build better financial habits.
Another cool feature is the real-time syncing. Whether you’re on your phone, tablet, or computer, your budget is always up to date. This is perfect for those of us who are constantly on the move and need to keep tabs on our spending.
Oh, and let’s not forget about the goal-setting feature. If you’ve got savings goals, YNAB helps you break them down into manageable chunks. It’s like having a little cheerleader in your pocket, keeping you motivated to save up for that dream vacation or emergency fund.
Now, I’ll be honest, YNAB isn’t free. But considering the value it offers, I’d say it’s worth the investment if you’re serious about taking control of your finances. They do offer a free trial, so you can test the waters before fully committing.
Also, the learning curve might be a bit steep for some. The app requires a bit of time to set up and understand fully. But hey, like most good things in life, it’s worth the effort.
It’s also worth mentioning that YNAB doesn’t automatically categorize your transactions like some other budgeting apps. You’ll need to do that manually, which can be a bit time-consuming. However, this does give you more control and accuracy over your budget.
All in all, YNAB is a solid choice if you’re looking to dive deep into budgeting and really get a handle on your finances. It’s not just about saving money; it’s about understanding your spending patterns and making informed financial decisions. The app encourages you to plan ahead, and that’s a game-changer for anyone looking to build a stable financial future.
If you’re ready to take your budgeting skills to the next level, give YNAB a shot. It might just be the tool you need to turn your financial life around. And hey, if you do decide to try it, let me know how it goes! I’d love to hear about your experience.
Pros and Cons
Pros
- Intuitive budgeting interface.
- Real-time expense tracking.
- Syncs across multiple devices.
- Customizable budget categories.
- Strong community support.
Cons
- Subscription required after trial.
- No direct bank syncing in some countries.
- Learning curve for beginners.
- Limited investment tracking.
- Requires regular manual updates.
Frequently Asked Questions
What is YNAB and how does it work?
YNAB, or You Need A Budget, is a personal finance app designed to help users manage their money effectively. It works by encouraging users to allocate every dollar they earn towards specific expenses, savings, and goals, fostering a proactive approach to budgeting. The app emphasizes planning for future expenses and adjusting budgets in real time.
Is YNAB suitable for beginners in budgeting?
Yes, YNAB is user-friendly and suitable for beginners. It offers comprehensive tutorials, guides, and workshops to help new users understand the basics of budgeting. Its intuitive interface and supportive community make it a great starting point for anyone looking to gain control over their finances.
Can YNAB connect to my bank accounts?
Yes, YNAB can securely connect to your bank accounts and import transactions automatically. This feature allows for seamless tracking of spending and ensures your budget is always up-to-date. Users can also enter transactions manually if they prefer not to connect their accounts directly.
What platforms is YNAB available on?
YNAB is available on multiple platforms, including Android, iOS, Windows, and macOS. This cross-platform availability ensures that users can access their budget and financial information from any device, whether at home or on the go, enhancing the app's versatility and convenience.
Is there a cost associated with using YNAB?
YNAB operates on a subscription model, offering a free trial period for new users. After the trial, users can choose to subscribe monthly or annually. While there is a cost, many users find the investment worthwhile due to the app's ability to help reduce unnecessary spending and improve financial health.

Download YNAB
Close Matches in This Category
 Google WalletFinance4.4
 Airtel: Recharge, Bank & LoansFinance4.0
 DANA Indonesia Digital WalletFinance4.5
 Binance: Buy Bitcoin & CryptoFinance4.8
 Inter Banking & Money TransferFinance4.4
 Cash AppFinance4.7
 PayPal - Pay, Send, SaveFinance4.2
 MetaTrader 5 — Forex, StocksFinance4.7